MARKET OVERVIEW

As of Close of 3rd Quarter 2026

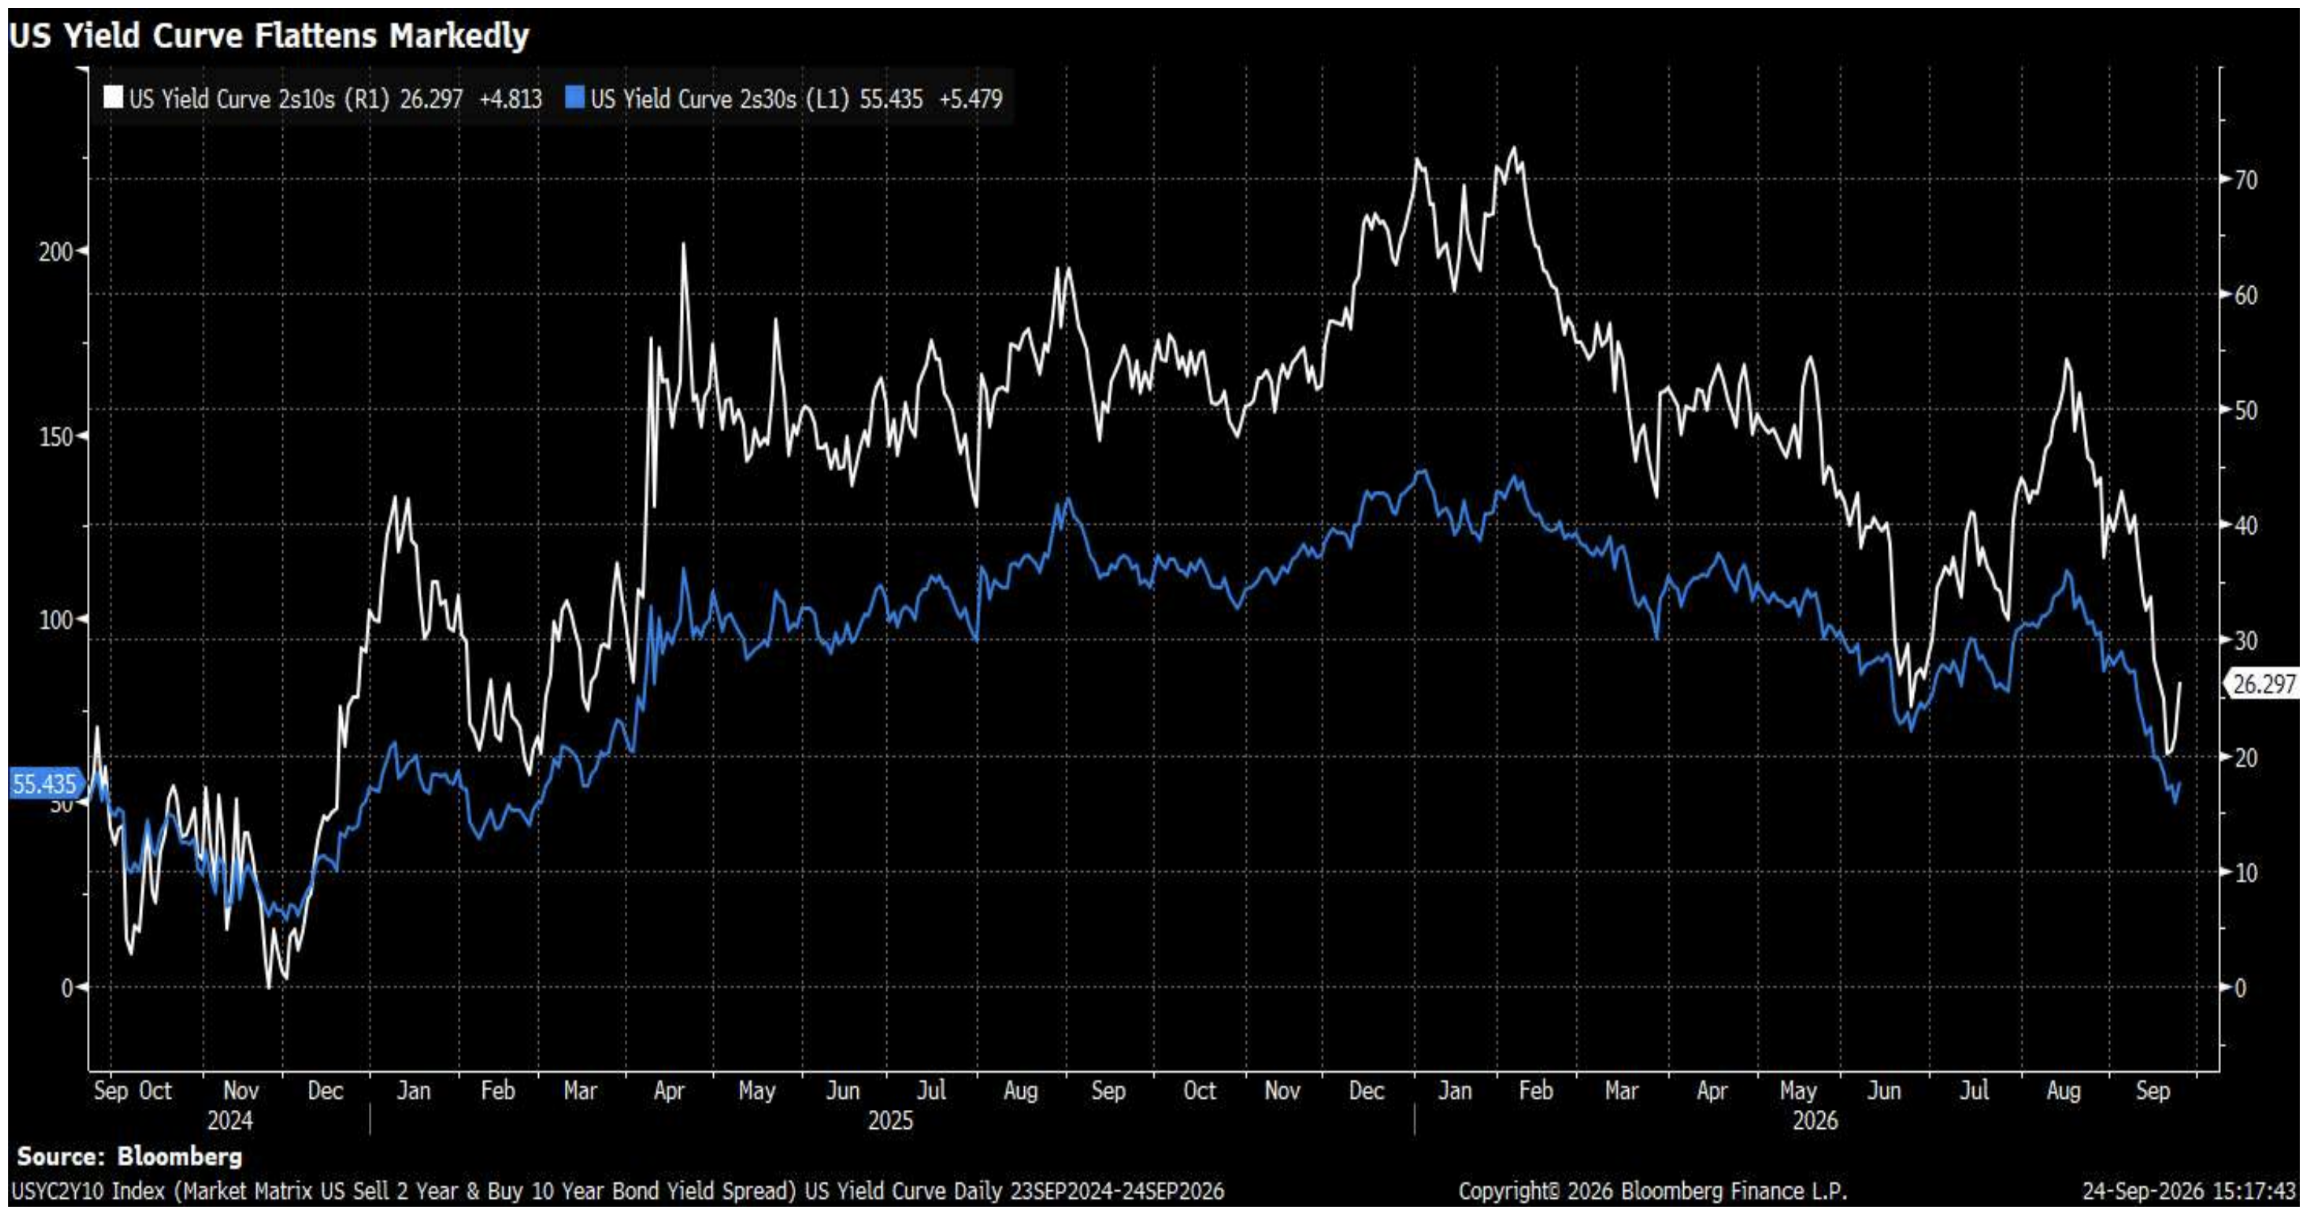
US Yield Curve Flattens

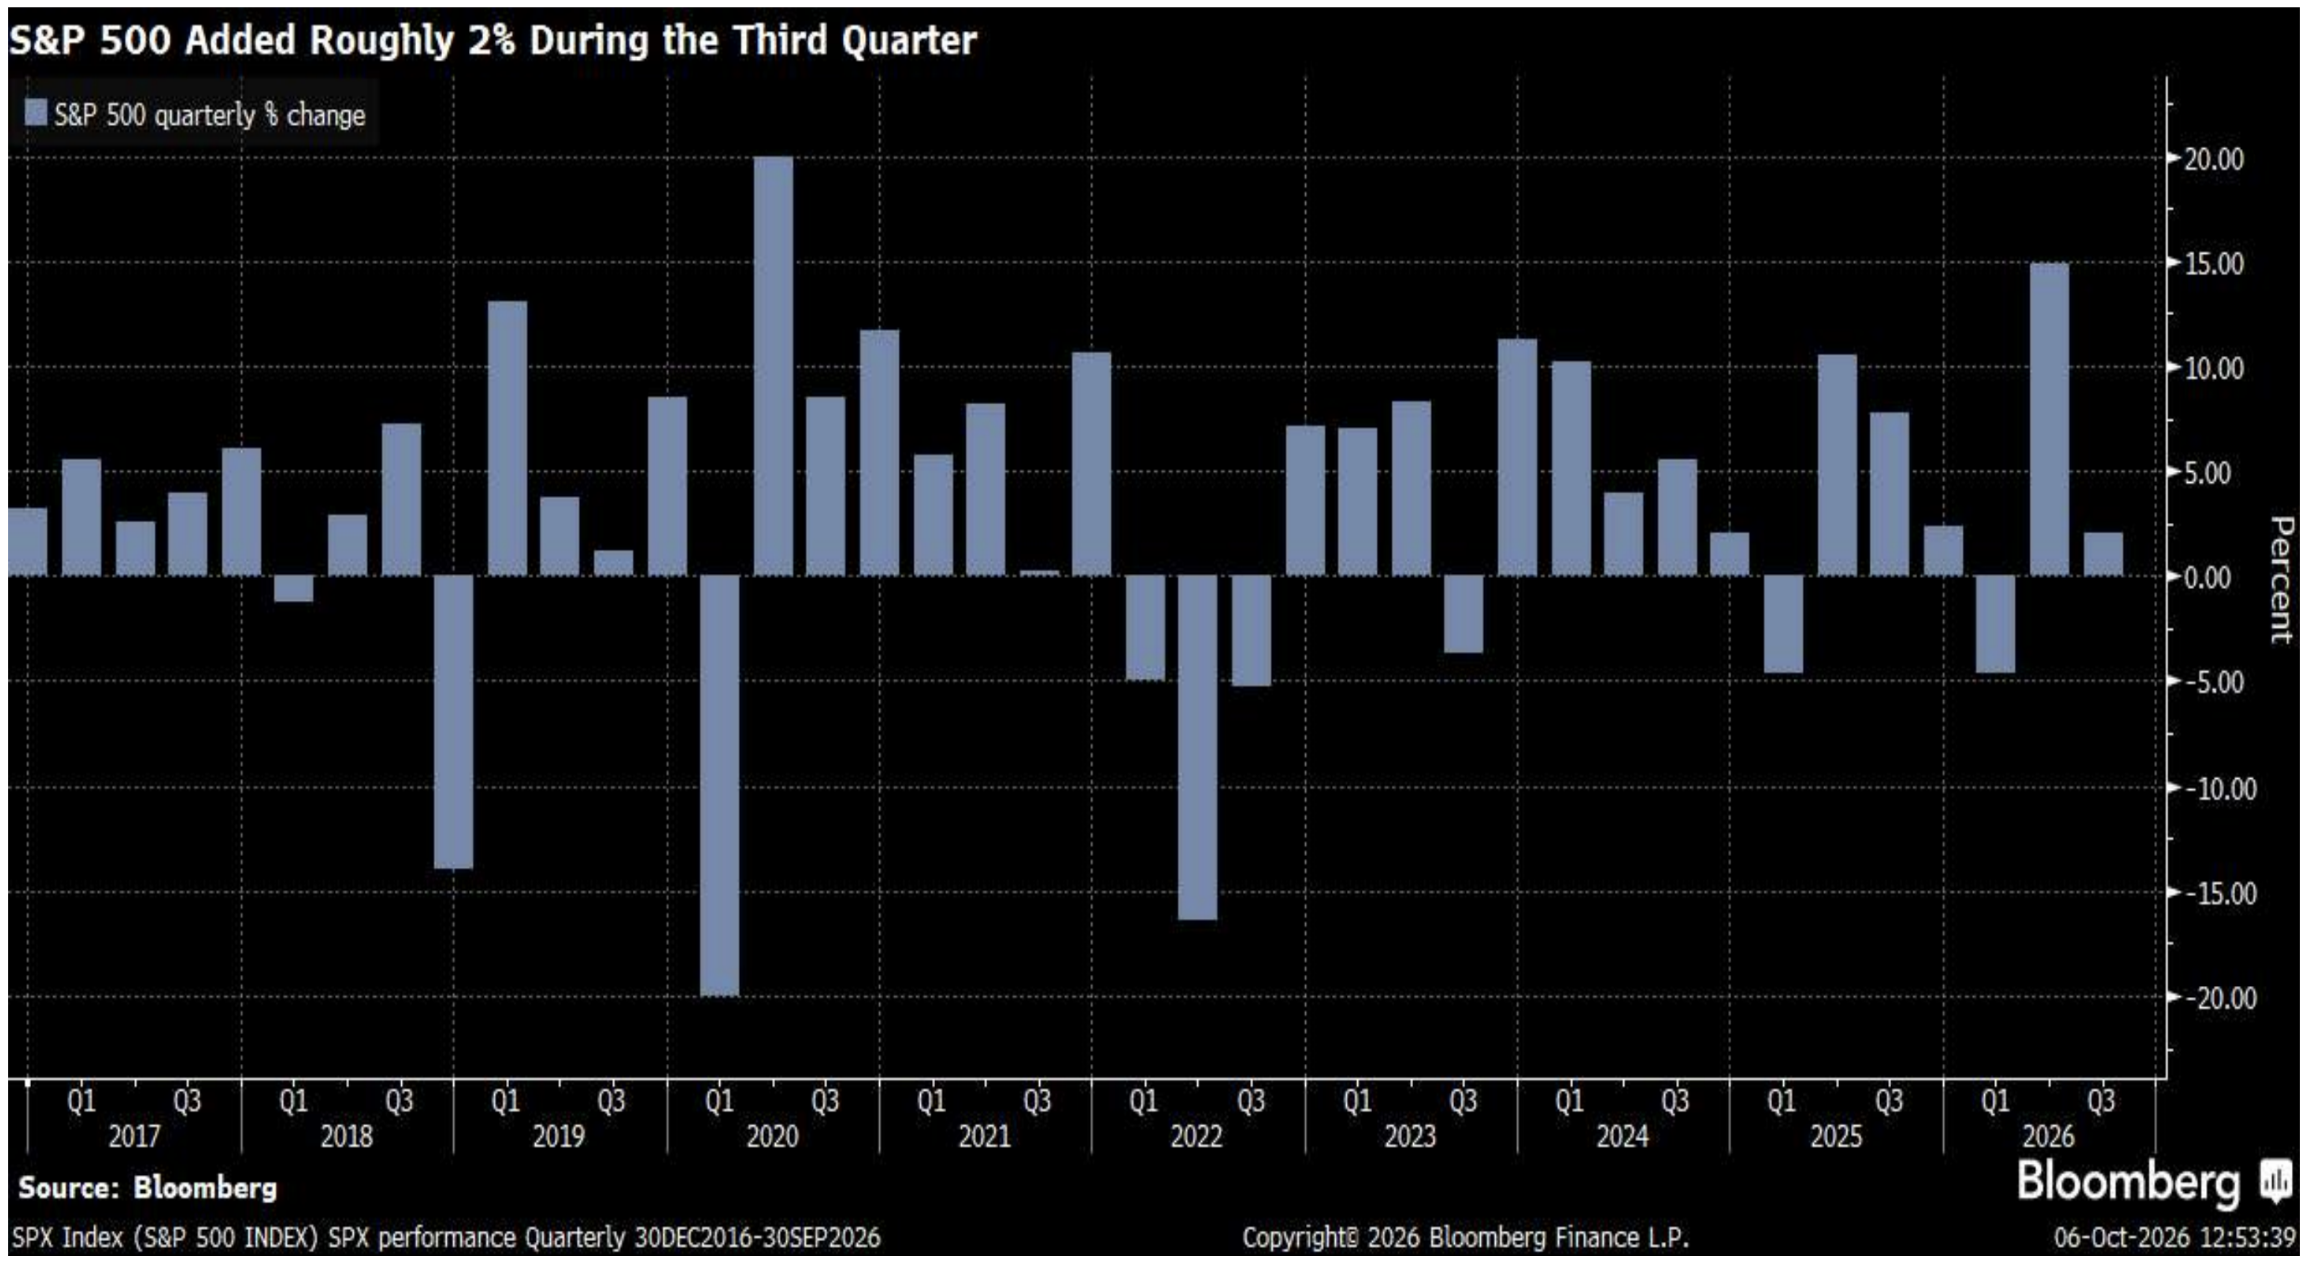
Modest Gains in the S&P

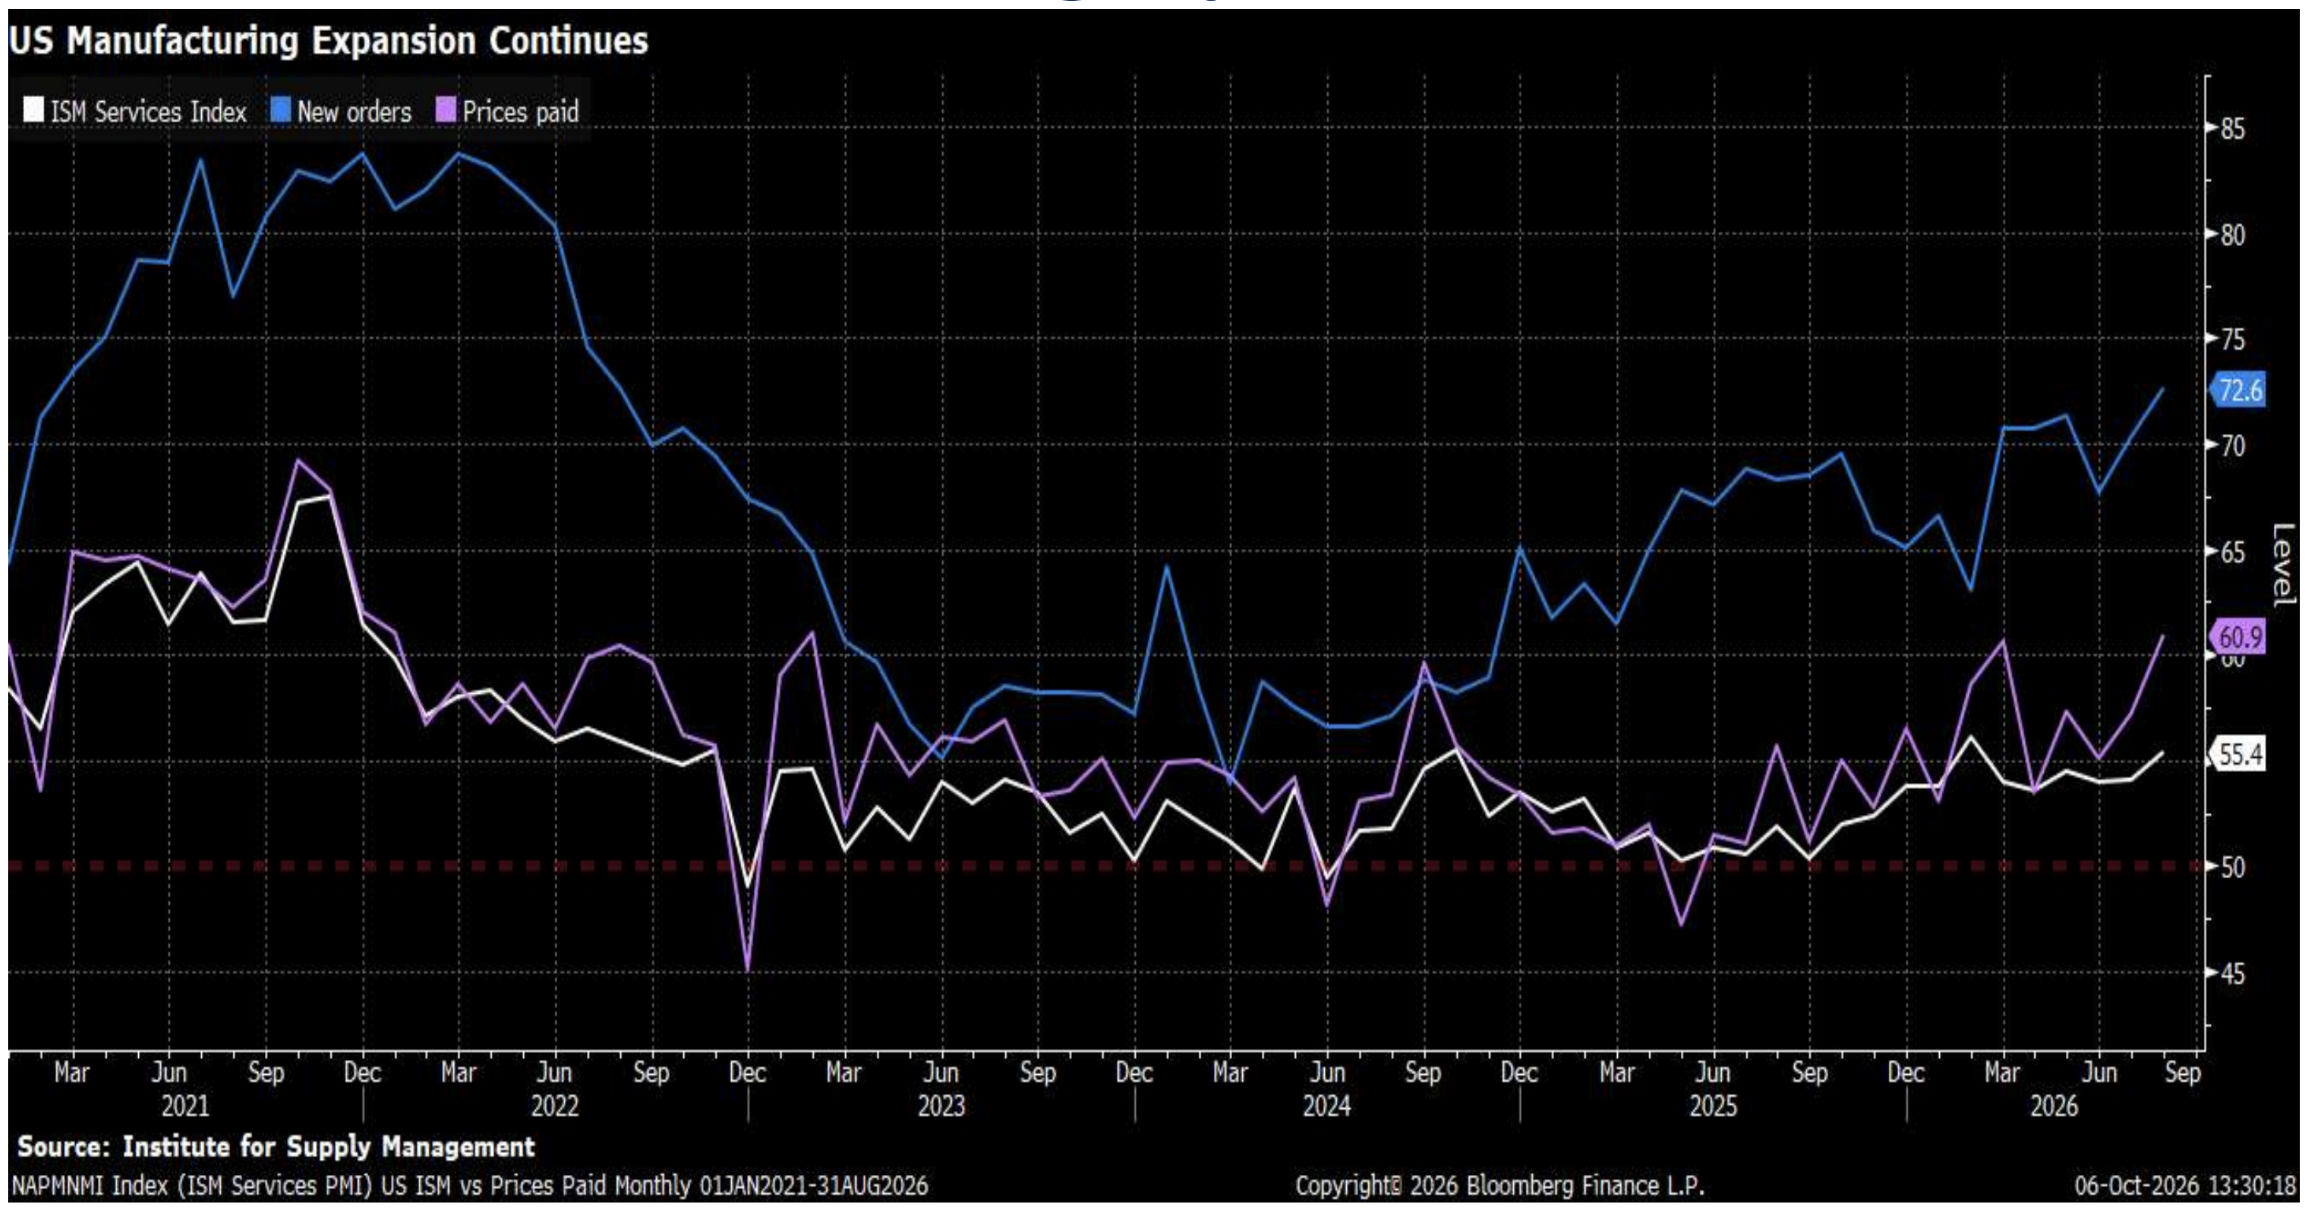
US Manufacturing Expansion Continues

Market Recap

  • Sticky inflation remains, resulting in the Federal Reserve raising fund rates by 25bps in September. Energy shocks disrupted the markets as brent crude oil surged roughly 40% in Q3, reaching over $100/barrel due to geopolitical tensions in the Middle East.

  • The S&P 500 finished Q3 2026 with a 2.3% gain. Small caps underperformed with Russell 2000 dropping 6.9%. Mega-caps and AI-linked stocks outperformed small caps

  • Interest rates spiked in Q3 causing US Treasury yields to reach their highest levels since 2007. Upward pressure on long term interest rates is coming from massive corporate debt issuance to finance AI projects and concerns over federal deficit spending. Corporate bond spreads remain tight due to solid investor demand seeking fixed income.

  • The U.S. labor market cooled significantly in the third quarter of 2026, highlighted by a weaker-than-expected September jobs report that showed job growth slowing.
Market Outlook

  • The equity market outlook for 2026 remains constructive, supported by resilient global economic growth, ongoing AI capital expenditure, and robust earnings momentum, tempered by valuation concentrations and elevated interest rate risks.
  • Inflation is projected to remain above the Federal Reserve’s 2% target due to structural pressures like tariffs and supply chain shifts, leading to a cautious, extended pause or slower easing cycle by the Fed. Persistent inflation and Federal Reserve policy shifts regarding higher-for-longer interest rates pose ongoing risks to long-duration assets.
  • Higher yields in the bond market present opportunities for fixed income investors, while equities are expected to outperform heading into 2027. Strong earnings continue to drive equities despite geopolitical tensions abroad and inflation concerns.